refi.
Most requested
Home loan refinancing
- Switch to a lower interest rate and reduce your monthly instalment
- Shorten or extend your tenure to suit your plans
- Full cost check first: lock-in penalty, legal fees, valuation and stamp duty
I'm BM Chew. I started banking at Standard Chartered in 2008, and today I help homeowners refinance smarter and buy the home they have been dreaming of.
Estimate my savings →Make your dream home come true.
I'm BM Chew. I started banking at Standard Chartered in 2008, and today I help homeowners refinance smarter and buy the home they have been dreaming of.
I am a banker, a property lover and a refinancing specialist. Since 2008 I have helped families pay less for their homes and move closer to the one they dream of.
Whether you are paying too much on your current loan, need funds for the next chapter, or are buying your first home, it starts with an honest look at your numbers.
Most requested
Unlock your equity
Buying your first home
How it works
Refinancing follows the same four stages every time. I handle the paperwork and keep you updated at each one.
Bring your latest loan statement. We look at your rate, balance, tenure and lock-in period.
I compare packages and show your real saving after legal fees, valuation and stamp duty.
The bank values your property and assesses your application. I prepare and follow up.
Sign the new facility. The new bank settles your old loan and any cash-out is released.
Enter your current loan details and a new rate to compare monthly instalments.
Example rates only, not a loan offer. The estimate excludes legal fees, valuation, stamp duty and lock-in penalties. Book a consultation for your actual figures.
About
I started my career at Standard Chartered in 2008, where I was recognised for customer acquisition and sales performance. Years inside a bank taught me how lenders assess a loan, what makes an application succeed, and where homeowners quietly lose money. BNA Harta is how I put that experience to work for you.
Recognition
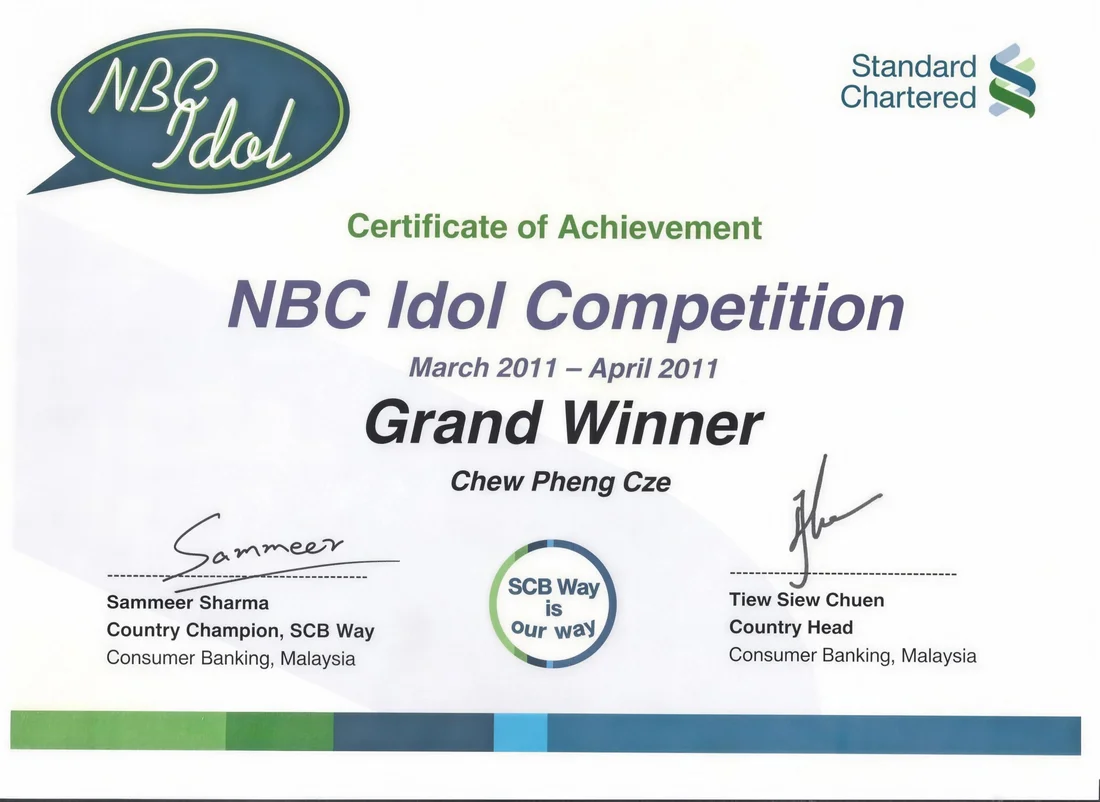
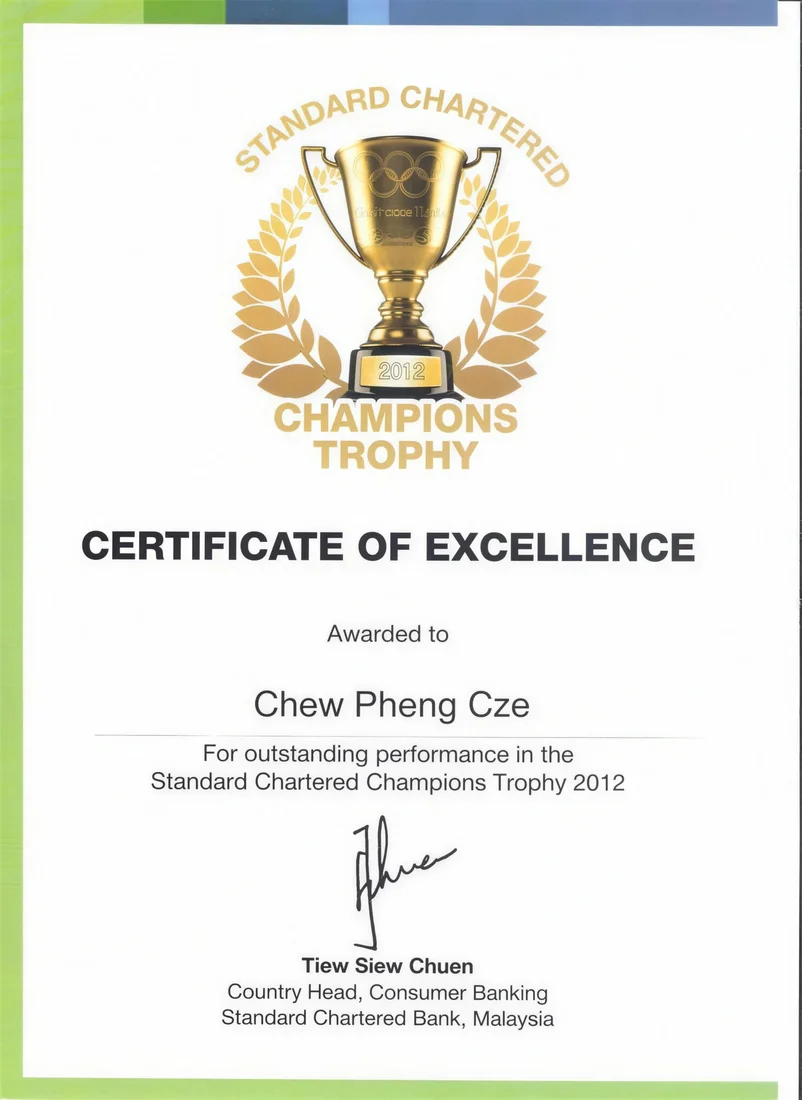
Certificate of Achievement from Standard Chartered Consumer Banking Malaysia, March to April 2011.
Three common situations I help homeowners with, and what the numbers can look like.
A homeowner with RM450,000 left on a 25-year loan moves from 4.75% to 4.05% once the lock-in period ends. The instalment drops from RM2,566 to RM2,388, about RM53,000 saved over the full tenure before switching costs.
A family owes RM300,000 at 4.6% and needs funds to renovate. Refinancing to RM400,000 at 4.1% over 25 years releases RM100,000, while the instalment rises by RM449 a month, from RM1,685 to RM2,133.
A first-time buyer looks at a RM500,000 home with 90% financing. A RM450,000 loan at 4.2% over 35 years comes to about RM2,047 a month. We check this against their DSR before they make an offer.
Illustrative examples using sample rates, not actual client cases or a loan offer. Your figures depend on your bank, income and property.
Know the terms
Banks use these every day. Knowing them puts you in a stronger position before you sign anything.
The bank's reference rate. Most home loans are priced as BR plus or minus a spread, so your rate moves when BR moves.
The share of your monthly income that goes to debt repayments. Banks use it to decide how much you can borrow.
The first few years of a loan when settling early triggers a penalty. Refinancing usually makes sense once it ends.
The percentage of the property value the bank will lend. The rest comes from your own funds.
Insurance that pays off the remaining loan if the borrower passes away or becomes disabled. Cover reduces as the loan does.
Borrowing more than your outstanding balance when you refinance, based on your home's current value.
FAQ
What homeowners ask most before refinancing.
Refinancing means replacing your current home loan with a new one, usually from another bank, to get a lower rate, a different tenure, or extra cash from your home's equity.
Usually after your lock-in period ends, when market rates are lower than what you pay, or when your property has gained value and you need funds. I can check your situation in one conversation.
Typical costs include legal fees, a valuation fee, stamp duty, and any lock-in penalty on your current loan. Some packages help cover part of these. I calculate them upfront so you see the real saving.
It depends on the bank, the valuation and the legal work. Many cases complete within a few months from application to release. I keep you updated at each stage.
Start with your IC, your latest loan statement, recent payslips or business income documents, and bank statements. I will send you a full checklist for your case.